USDA loan
Zero down beyond the city limits
100% financing in eligible suburban and rural areas, with income limits and low guarantee fees.
The short version.
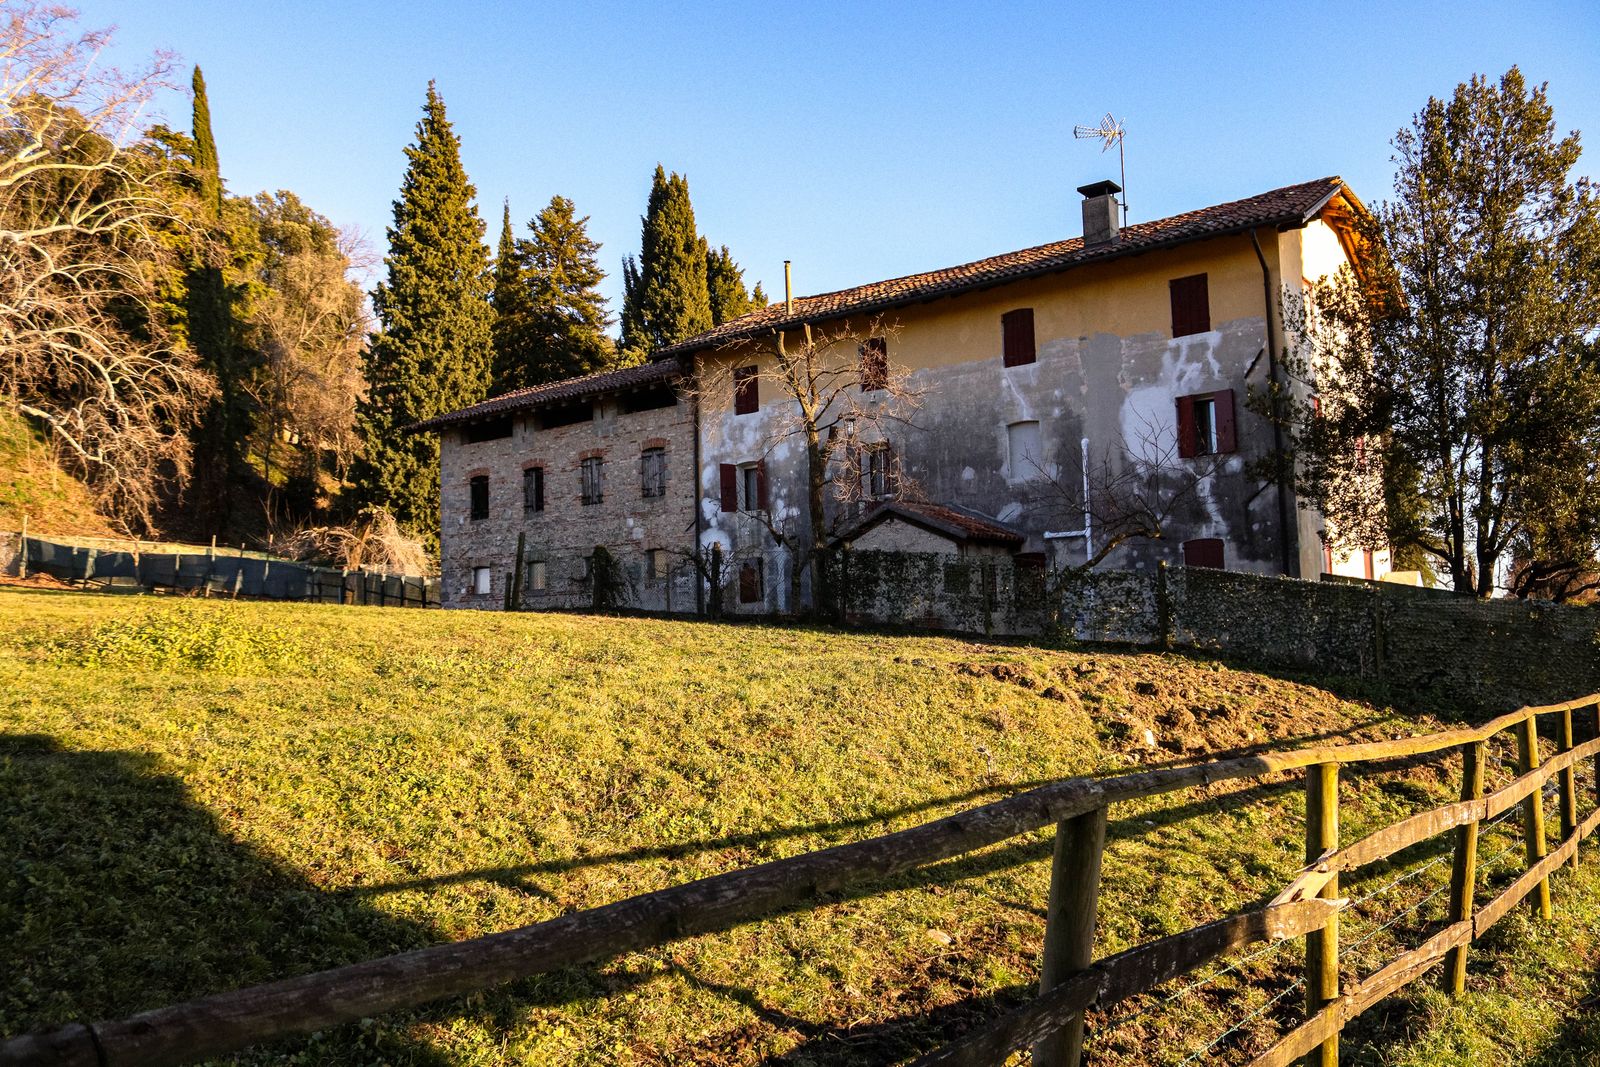
USDA Rural Development loans offer no-down-payment financing in eligible areas, and more of Central Florida qualifies than people expect. Parts of Clermont, St. Cloud, Groveland and east Orange County have eligible addresses just minutes from major employers.
Household income must fall under the area limit, which counts everyone living in the home. The guarantee fee is lower than FHA mortgage insurance, which often makes USDA the lowest-payment option for buyers who qualify.
Often the right fit for
- Moderate-income households
- Buyers open to Lake or Osceola County
- Families wanting more land
What I handle for you.
- Address eligibility check before you tour
- Household income calculation with allowable deductions
- USDA vs FHA payment comparison
- Seller-paid closing cost structuring
- Guidance on USDA approval timelines
- Well and septic inspection checklist
Map and income check
We confirm the neighborhoods you like are eligible and that household income fits.
Lender and USDA approval
Your file is approved by our underwriter, then receives the USDA guarantee.
Close with patience
Allow a little more time, usually 30 to 40 days, for the government review.
Why borrowers choose it.
100% financing
Buy with no down payment and roll in the guarantee fee.
Low annual fee
0.35% annual fee is well below FHA monthly premiums.
More space
Eligible areas often mean larger lots and newer builds.
What moves your approval and price.
These are the factors I review first. Every lender adds its own overlays, which is why comparing matters.
| Factor | What to know |
|---|---|
| Location | The property address must be in a USDA eligible area on the official map. |
| Household income | All adult household income counts, even if not on the loan. |
| Occupancy | Primary residence only, no working farms or income-producing land. |
| Timeline | Plan for 30 to 40 days due to the USDA final review. |
USDA questions, answered.
Still wondering about something specific? Text or call and you will hear back from Marcus, usually within two hours.
No. Many eligible homes are in regular subdivisions with city water and HOA amenities. The program is about location, not agriculture.
There is no set price cap for the guaranteed program, but your income and debt ratios determine what you qualify for.
Often yes. Assistance can cover closing costs and prepaid items so you bring very little to closing.
Related programs.
VA loan
No down payment, no monthly mortgage insurance and funding fee exemptions for disabled veterans.
Explore VA
FHA loan
3.5% down with a 580 score, higher debt-to-income flexibility and gift-friendly down payment rules.
Explore FHA
Conventional loan
As little as 3% down for first-time buyers, mortgage insurance that falls off, and terms from 10 to 30 years.
Explore Conventional
A note from Marcus
Get real answers in twenty minutes.
No credit pull, no pressure. Bring your questions and leave with a clear plan and real numbers.