Marcus Bell, your mortgage advisor in Orlando
Your mortgage,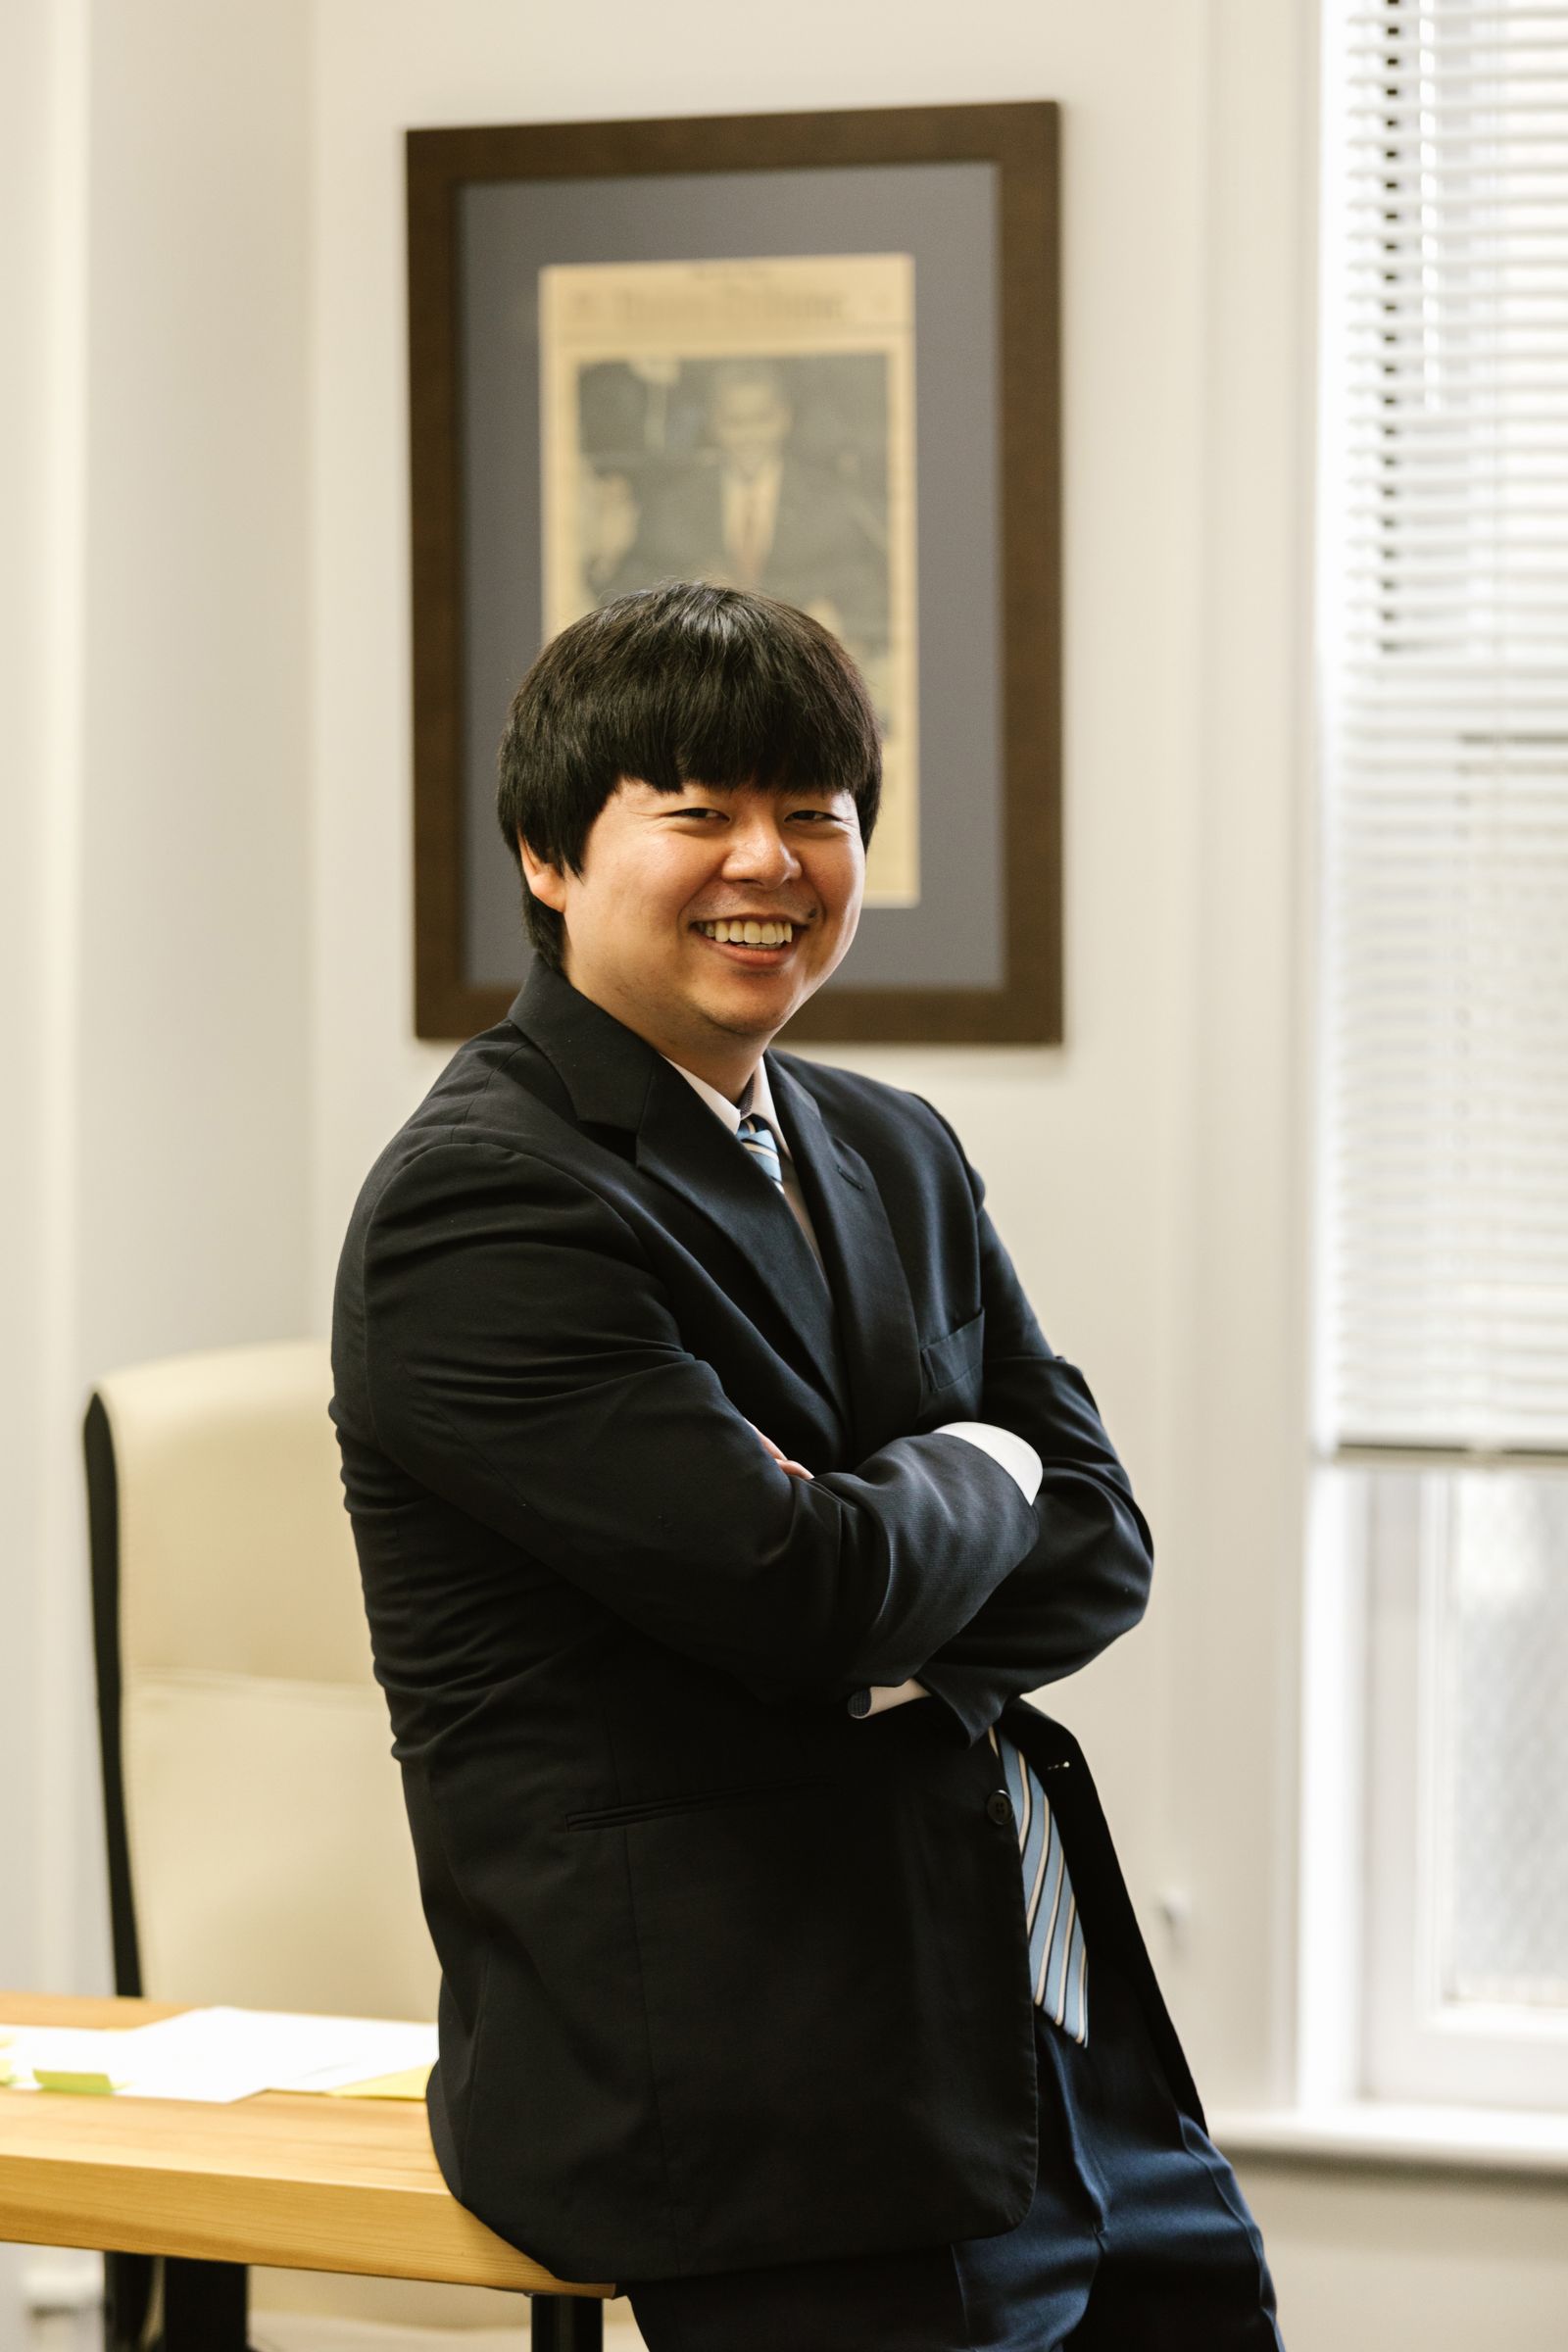 explained by a real person.
Straight answers, honest math and one phone number from first question to closing day. First-time buyers, business owners and veterans welcome.
- 4.9 from 612 reviews (sample)
- 24 hr typical pre-approval
- NMLS #000000 placeholder
Meet Marcus
Fifteen years in lending, still answering his own phone.
I started as a bank teller in Parramore watching neighbors get turned away for loans they could afford. Now I make sure nobody leaves a conversation more confused than when they arrived.
 Why I left the big bankRead the story, 3 min
Explains before he sells
Every option shown side by side with total cost, not just the monthly payment.
Answers after 6 pm
Texts and calls returned the same evening, because offers do not wait for business hours.
Shops lenders for you
One application compared across several wholesale lenders (demo description).
Eight loan programs. One person who knows which fits.
Hover or tap a program for the short version, then open the full breakdown with qualifying factors and sample numbers.
Compare all programs ConventionalAs little as 3% down for first-time buyers, mortgage insurance that falls off, and terms from 10 to 30 years.
 FHA3.5% down with a 580 score, higher debt-to-income flexibility and gift-friendly down payment rules.
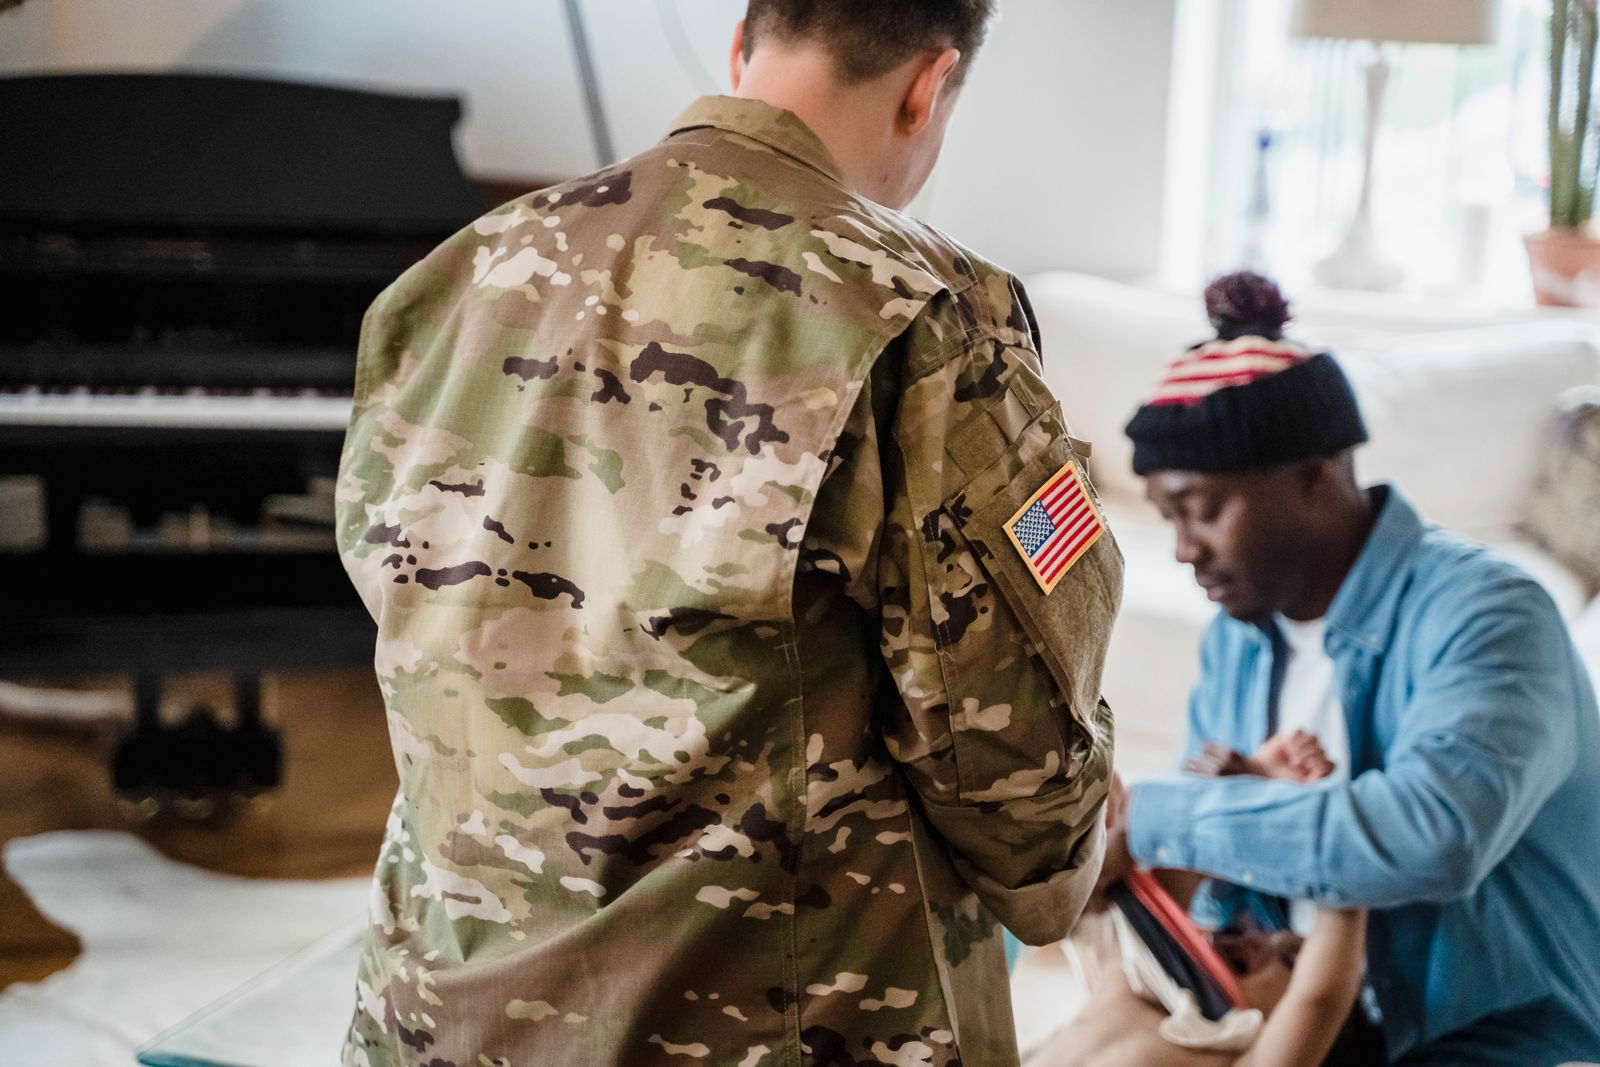 VANo down payment, no monthly mortgage insurance and funding fee exemptions for disabled veterans.
 USDA100% financing in eligible suburban and rural areas, with income limits and low guarantee fees.
 JumboLoan amounts above conforming limits with 10% down options and reserves-based underwriting.
 Bank statement12 or 24 months of personal or business bank statements replace tax returns for self-employed buyers.
 DSCR investorQualify with the property's rent instead of personal income. LLC vesting and short-term rentals allowed.
 RefinanceRate-and-term, cash-out, FHA streamline and VA IRRRL options, with a break-even analysis every time.
Built for the files other lenders call complicated.
Most of my clients are not a textbook W-2 file. That is exactly the point.
Not sure where you fit?
Five questions, two best-fit programs.
Answer a few quick questions and Marcus calls back with the programs that make the most sense.
Start my application
41%
of Marcus's 2025 closings were self-employed, veteran or relocation files (sample).
Day 1
Talk it through
A 20-minute call about goals, budget comfort and timing. No hard credit pull, no forms.
Day 2 to 3
Get verified pre-approval
Upload documents from your phone. I review them personally and an underwriter signs off.
Day 21 to 30
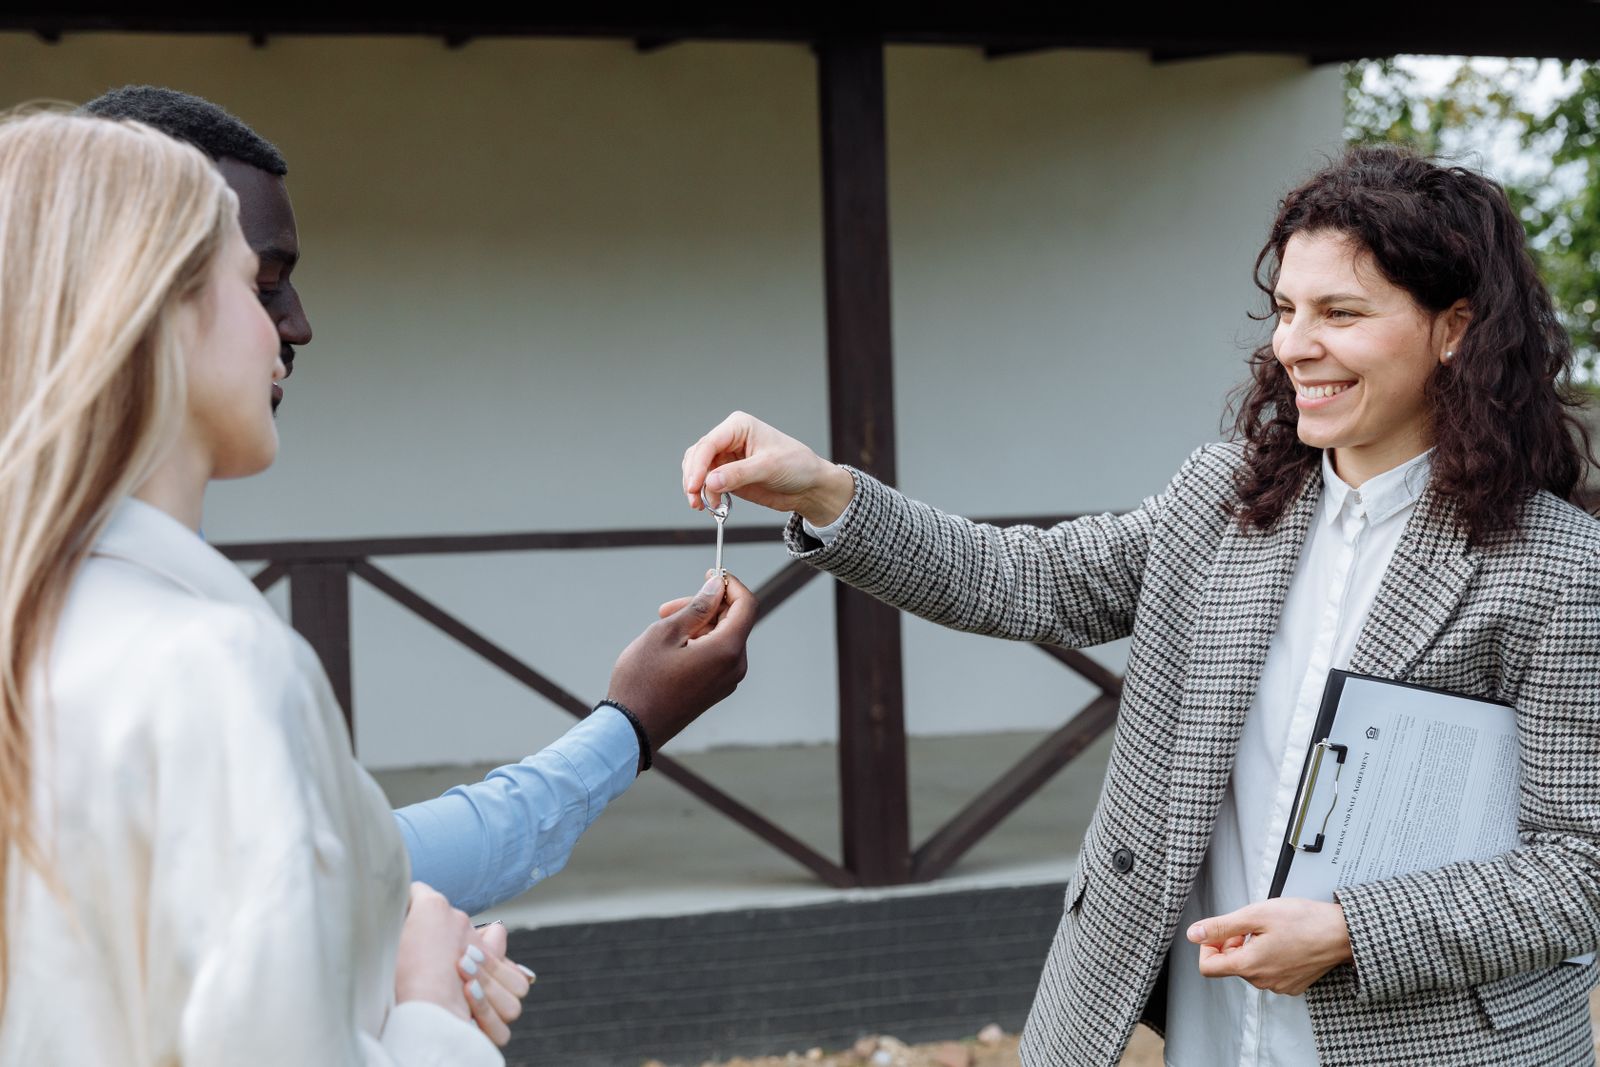
Lock, close, get keys
Friday status texts, a Closing Disclosure walkthrough, and a closing date that holds.
“Nobody should sign a thirty-year promise they do not fully understand. If I cannot explain it on a napkin, it is not the right loan.”
Renting versus owning, side by side.
Drag the slider. For a lot of my Kissimmee and Sanford clients the monthly number barely changes. What changes is who keeps the equity.
- Monthly housing cost
- $2,150 rent$2,240 PITI
- Equity after 5 years
- $0$58,400
- Rent or payment increases
- 6% a yearFixed P&I
Sample illustration only: $365,000 purchase, 3.5% down, 6.25% rate, 3% annual appreciation. Not a quote.
Run your own numbers Owning
 Renting
What to gather before we talk.
You do not need all of this for the first call. Having it ready is how pre-approvals happen in a day instead of a week.
- Last 30 days of pay stubsOr a signed offer letter if you are relocating
- Two years of W-2s or 1099sSelf-employed? Add two years of returns
- Two months of bank statementsEvery page, even the blank ones
- Retirement and brokerage statementsHelps with reserves on larger loans
- Photo ID for each borrowerDriver license or passport
- Gift letter, if family is helpingI send you a ready-to-sign template
- DD-214 or statement of serviceFor VA loans only
- Current mortgage statementFor refinances and move-up buyers
- Divorce decree or child support orderOnly if it applies to you
- Explanation of recent credit inquiriesA sentence or two is plenty
Featured client story
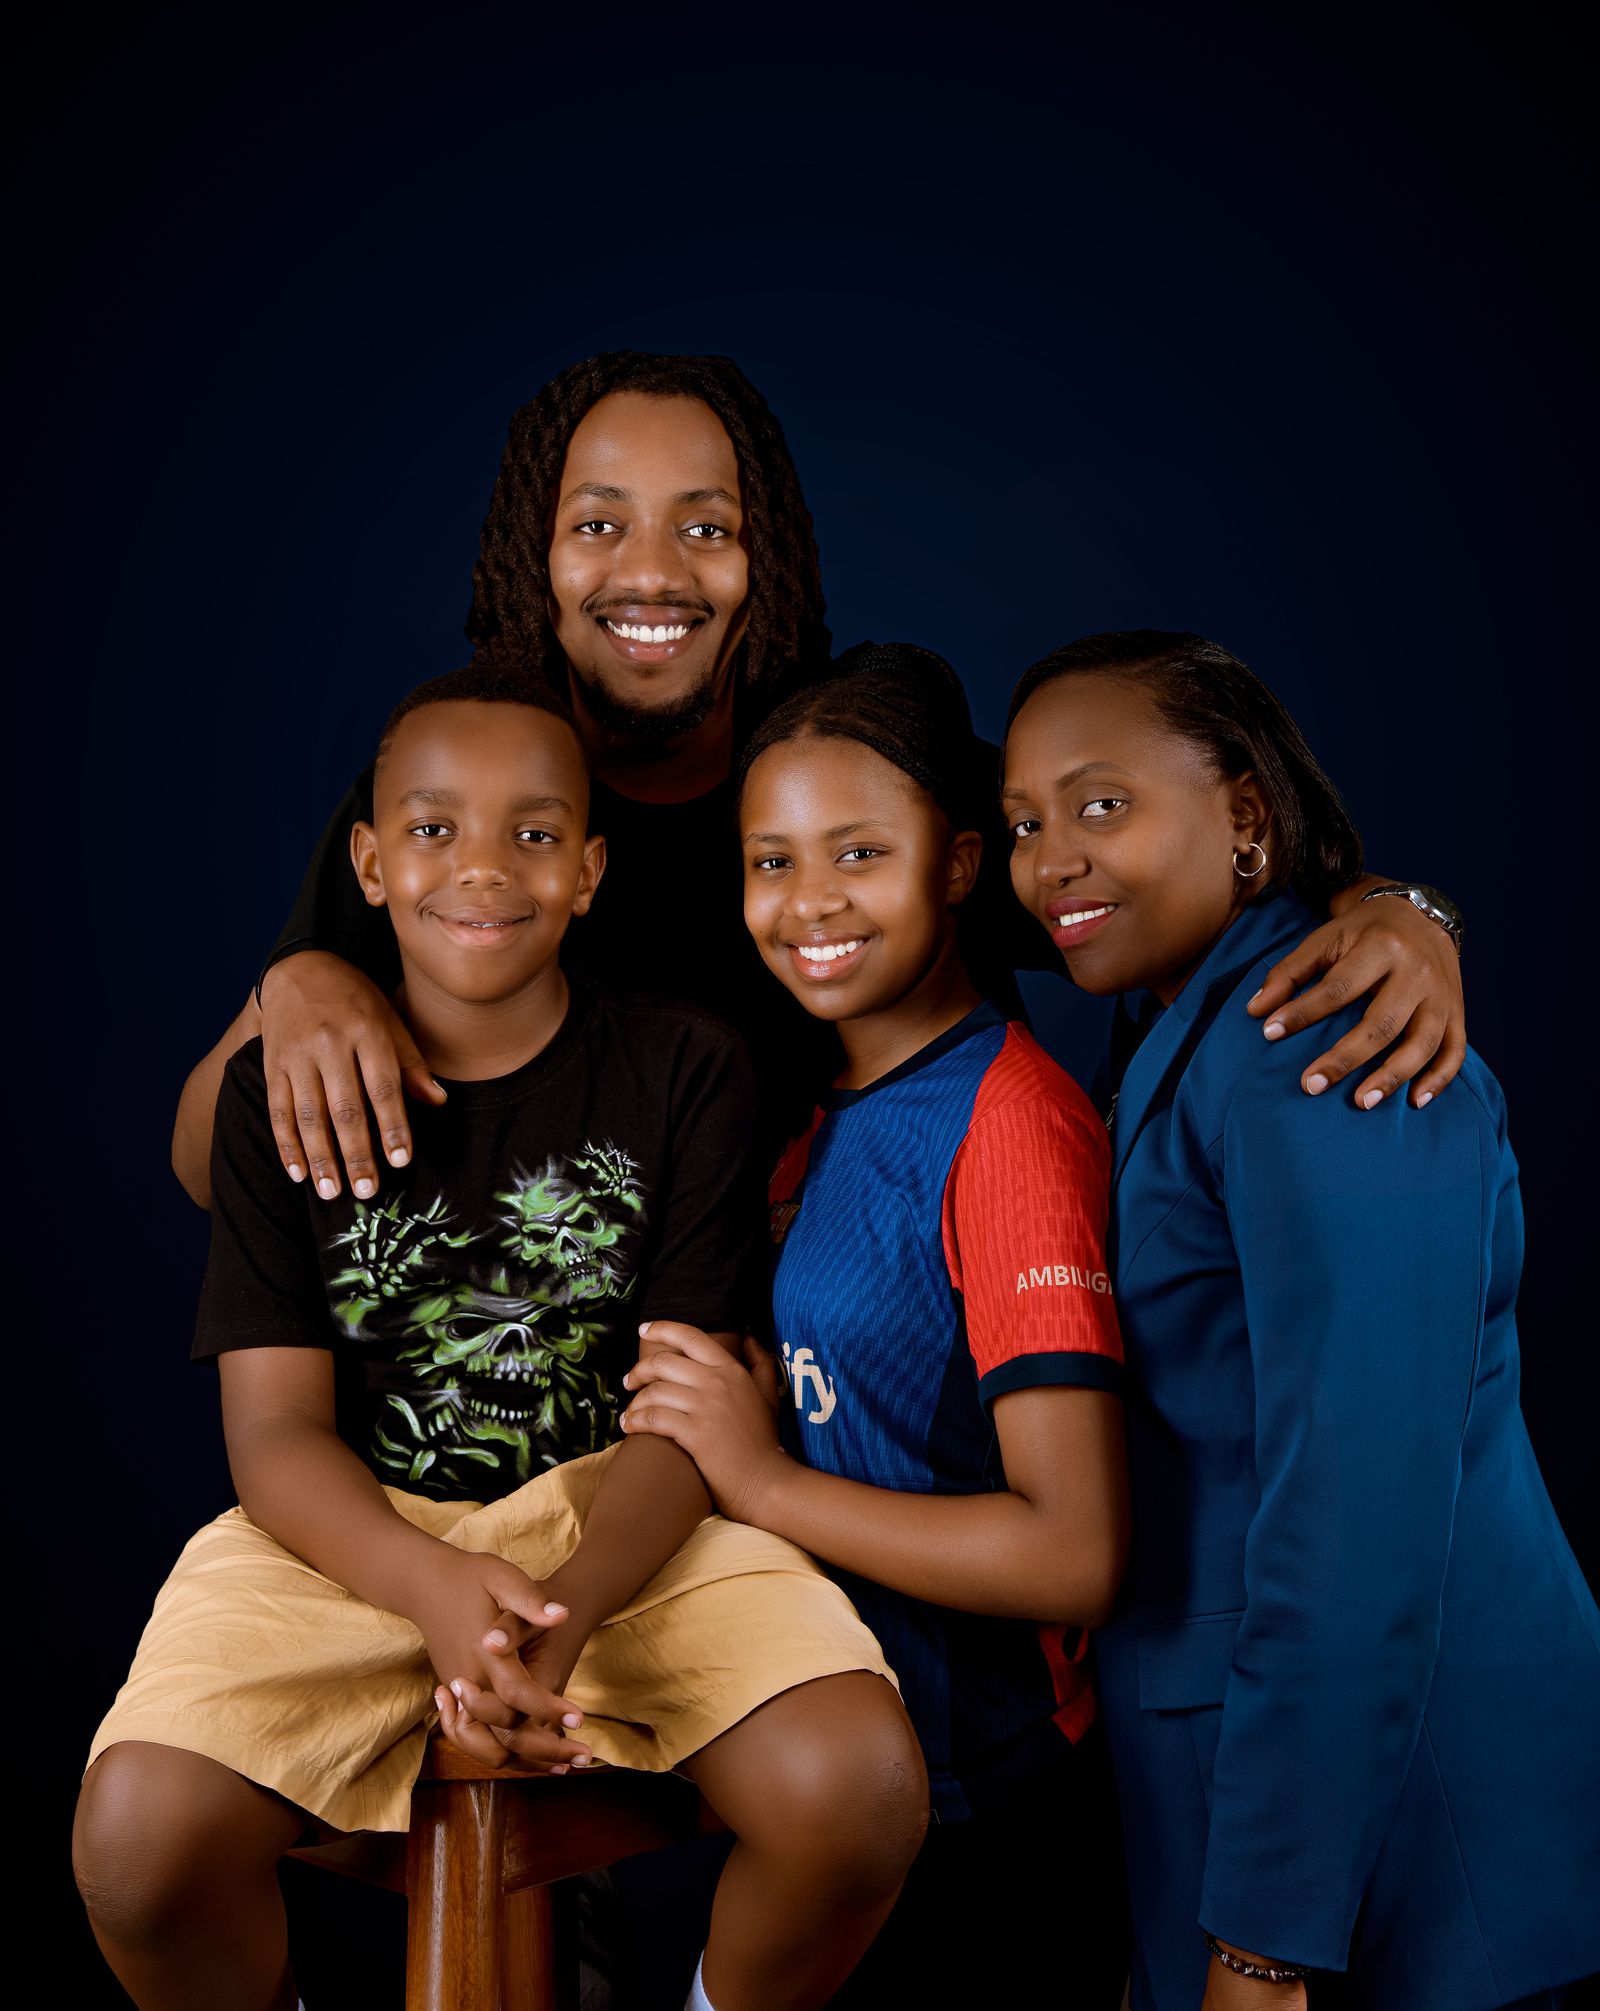
Two lenders told us to come back in a year. Marcus sat with us for an hour, found an assistance program we qualified for and walked us through every number. We closed in 26 days and still text him questions about our escrow.
- FHA purchase
- Closed in 26 days
- $11,500 assistance (sample)
Meet in person, over coffee or on video.
Pick whatever fits your day. Most first calls happen by phone, and most closings happen within twenty minutes of one of these spots.
All areas servedDowntown Orlando office
200 S Orange Ave, Suite 1450
Orlando, FL 32801Today 8:00 am - 7:00 pm
Free validated parking in the Orange Ave garage.
Winter Park coffee meetings
Near 300 N Park Ave
Winter Park, FL 32789Today by appointment
Saturday morning meetings for busy schedules.
Lake Nona video suite
Near 6900 Tavistock Lakes Blvd
Orlando, FL 32827Today 7:00 am - 9:00 pm
Video calls for relocating buyers in any time zone.
For realtors
Your buyers, pre-approved like they mean it.
- Underwriter-reviewed approvals your listing agents can verify by phone
- Friday status updates to you and your buyer, without you chasing
- Co-branded open house payment sheets within 24 hours (sample)
Questions people ask on the first call.
Still wondering about something specific? Text or call and you will hear back from Marcus, usually within two hours.
No. The 20-minute strategy call is free, and there is no hard credit pull until you decide to move forward with a pre-approval.
FHA can work from 580, most conventional loans start around 620, and VA lenders typically look for 600 or higher. Better scores unlock better pricing, and I can share a plan to improve yours.
It can be 0% with VA or USDA, 3% with conventional first-time buyer programs, or 3.5% with FHA. Plan for closing costs of roughly 2% to 4% too, which seller credits can often cover.
Most purchases close in 21 to 30 days. USDA and some condo purchases take closer to 35 to 45 days.
Yes. With two years of history you may qualify with tax returns, or with a bank statement loan that uses deposits instead of taxable income.
A note from Marcus
Get real answers in twenty minutes.
No credit pull, no pressure. Bring your questions and leave with a clear plan and real numbers.