Jumbo loan
Financing for Winter Park and waterfront prices
Loan amounts above conforming limits with 10% down options and reserves-based underwriting.
The short version.
When a loan amount exceeds the conforming limit, it becomes a jumbo loan. In Winter Park, Windermere, Isleworth and along the Butler Chain of Lakes, jumbo financing is common rather than exotic.
Jumbo lenders look closely at reserves, meaning liquid assets left after closing, and at how stable your income is. I shop several jumbo investors because pricing and guidelines vary widely, especially for business owners and physicians.
Often the right fit for
- Luxury and lakefront buyers
- Physicians and executives
- Buyers relocating with equity
What I handle for you.
- Multi-investor jumbo pricing comparison
- Reserve strategy using retirement accounts
- Bridge options to buy before you sell
- Appraisal management for unique properties
- Private client pace with extended hours
- Coordination with your CPA and advisor
Asset and income review
We map reserves, bonuses and RSUs so underwriting sees your full strength.
Investor match
I compare jumbo investors for rate, down payment and property type fit.
Full appraisal and close
Higher-value homes may need two appraisals, which I plan into the timeline.
Why borrowers choose it.
Less down than you think
Qualified buyers can put 10% down without mortgage insurance.
Relocation friendly
Buy-before-you-sell options for moves from out of state.
Interest-only options
Available on select jumbo programs for cash-flow planning.
What moves your approval and price.
These are the factors I review first. Every lender adds its own overlays, which is why comparing matters.
| Factor | What to know |
|---|---|
| Reserves | Most investors want 6 to 12 months of payments in liquid or retirement assets. |
| Debt-to-income | Usually capped at 43% for the best pricing. |
| Appraisal | Loans over $1.5 million may need a second appraisal. |
| Income documentation | Two years of history, with bonus and commission averaged. |
Jumbo questions, answered.
Still wondering about something specific? Text or call and you will hear back from Marcus, usually within two hours.
Not necessarily. Jumbo pricing is set by each investor and is sometimes equal to or better than conforming rates for strong borrowers.
Yes. Vested stock typically counts at 70% of its value toward reserves, and some investors use RSU income for qualifying.
Some do, but several of the investors I work with allow 10% down on primary residences with strong credit.
Related programs.
Conventional loan
As little as 3% down for first-time buyers, mortgage insurance that falls off, and terms from 10 to 30 years.
Explore Conventional
Bank statement loan
12 or 24 months of personal or business bank statements replace tax returns for self-employed buyers.
Explore Bank statement
Refinance
Rate-and-term, cash-out, FHA streamline and VA IRRRL options, with a break-even analysis every time.
Explore Refinance
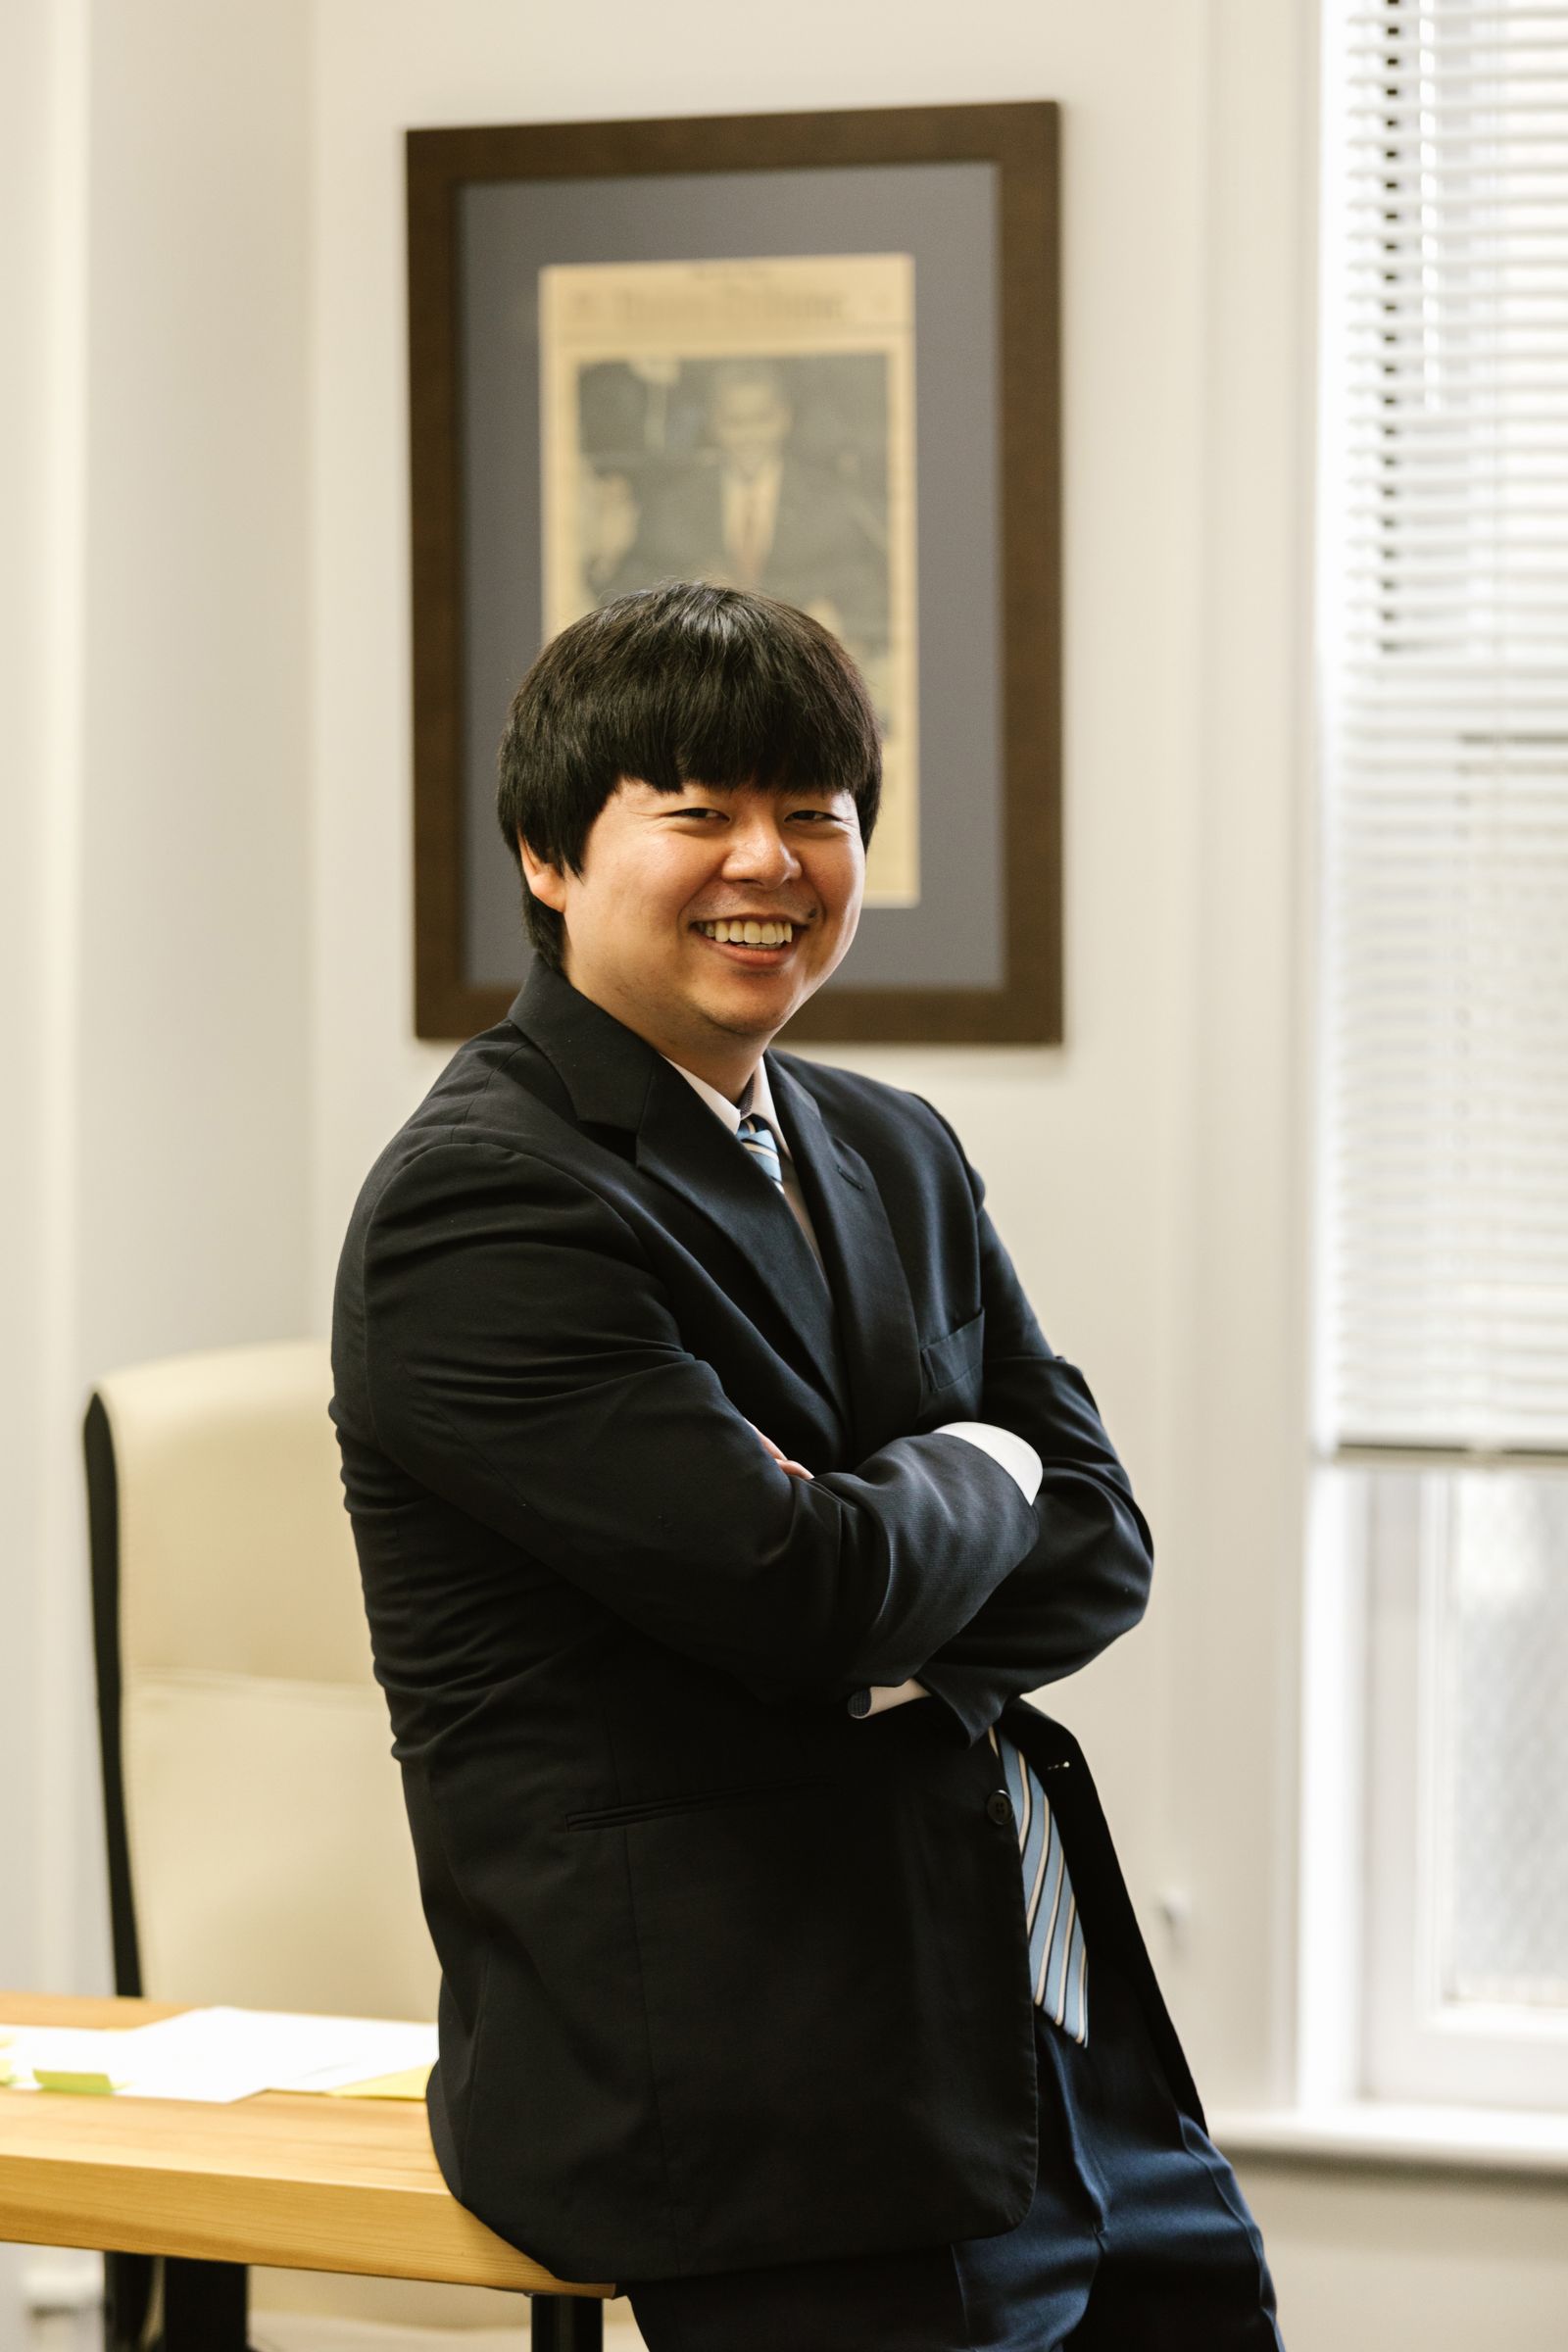
A note from Marcus
Get real answers in twenty minutes.
No credit pull, no pressure. Bring your questions and leave with a clear plan and real numbers.